Is Alimony Taxable in North Carolina? What Divorcing Spouses Need to Know
Alimony awards in North Carolina remain highly discretionary and fact-specific. Unlike child support, there is no formula or calculator that can reliably predict whether alimony will be awarded or, if it is awarded, the amount and duration of support.
How the Tax Cuts and Jobs Act Changed Alimony Taxation
Today, the rules are different.
For divorce decrees and separation agreements executed after December 31, 2018, alimony payments are generally not deductible by the paying spouse and are not taxable income to the receiving spouse. Divorce and separation instruments executed on or before December 31, 2018 generally remain subject to the prior tax treatment unless they are modified and expressly adopt the current federal tax rules. (IRS Topic 452, IRS FAQ)
How Does the Current Tax Law Affect Alimony Negotiations?
The elimination of the federal alimony deduction changed the economics of many divorce settlements.
Under the former system, a supporting spouse often received a tax benefit from paying alimony, making larger support payments more affordable. Because that deduction is no longer available in most new cases, some supporting spouses may be less willing to agree to higher alimony payments during settlement discussions.
For dependent spouses, the change can be a mixed result. While recipients no longer pay federal income taxes on alimony received under post-2018 agreements, supporting spouses are making those payments with after-tax dollars. As a result, the overall value of an alimony arrangement may be negotiated differently than it would have been under the prior tax rules.
Every case is unique. The impact of the current tax treatment may vary depending upon the parties’ incomes, tax brackets, property division, and other financial considerations.
How Do North Carolina Courts Consider Taxes?
North Carolina courts maintain broad discretion when determining whether alimony should be awarded and, if so, the amount, duration, and method of payment.
Under N.C.G.S. § 50-16.3A, the court must consider numerous factors, including:
Although federal tax law no longer provides an alimony deduction in most new cases, tax consequences remain one factor that courts may consider when evaluating alimony claims.
Frequently Asked Questions
Are pre-2019 alimony agreements still deductible?
Yes, many pre-2019 agreements remain grandfathered under the prior tax rules. Generally, if a divorce decree or separation agreement was executed on or before December 31, 2018, alimony payments remain deductible by the payer and taxable to the recipient. The parties continue to receive the benefit of the old tax treatment unless a later modification expressly provides that the new federal rules apply. As a result, individuals who have been paying or receiving alimony for many years should not assume their tax treatment has changed. The date of the agreement and the language of any modifications are critically important.
Can a modified agreement lose its grandfathered tax treatment?
Potentially, yes. Under federal law, a pre-2019 divorce decree or separation agreement may become subject to the current tax rules if it is modified after December 31, 2018 and the modification expressly states that the repeal of the alimony deduction applies to the modified agreement. However, not every modification automatically results in the loss of grandfathered treatment. The specific language contained in the modification is important. Before agreeing to modify an existing alimony obligation, parties should carefully review the tax consequences with their attorney and tax professional.
What about prenuptial and postnuptial agreements?
Prenuptial and postnuptial agreements often address the issue of spousal support, but the federal tax treatment ultimately depends upon the divorce decree, separation agreement, or other qualifying divorce or separation instrument under which alimony is paid. As a result, many older prenuptial agreements were drafted with assumptions about tax deductibility that no longer apply to divorces finalized after December 31, 2018. Parties negotiating or enforcing a premarital agreement should consider how current federal tax law affects the practical value of any alimony provisions.
Why does tax planning still matter in divorce cases?
The tax treatment of alimony changed, but tax planning remains an essential part of any divorce settlement. Issues involving retirement accounts, investment assets, capital gains, filing status, dependency exemptions, business ownership interests, and property division can all carry significant tax implications. In many cases, the long-term tax consequences of a settlement are just as important as the amount of support being paid or received. Careful planning can help spouses evaluate the true value of a proposed settlement and avoid unintended financial consequences after the divorce is finalized.
What Should You Do If Alimony Is an Issue in Your Divorce?
Whether you expect to pay alimony or receive it, understanding the tax consequences remains an important part of evaluating settlement options. The structure of support, property division, retirement assets, and other financial terms can have a significant impact on your long-term financial outcome.
An experienced North Carolina family law attorney can help you understand how current tax rules and North Carolina’s alimony laws may affect your particular circumstances.
At McIlveen Family Law Firm, we help clients evaluate alimony claims, negotiate favorable settlements, and develop strategies designed to protect their financial future.
This article is provided for informational purposes only and does not constitute legal advice. Laws may change, and the outcome of any particular case depends upon its specific facts and circumstances.
Explore More
Have Questions About Alimony and Taxes?
Our family law attorneys can help you understand how tax law affects your alimony claim or obligation.
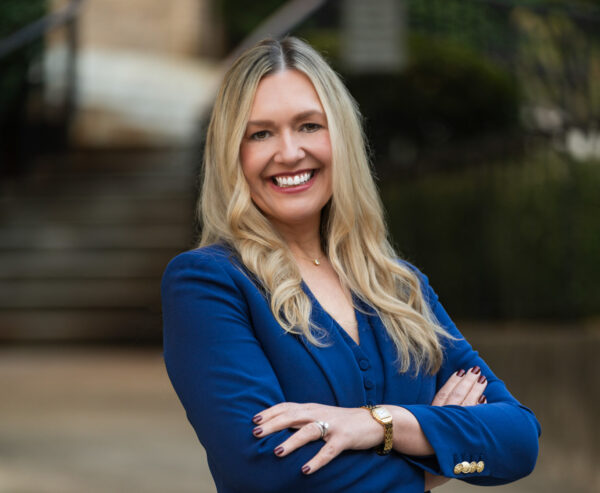
Managing Partner and Co-Founder, McIlveen Family Law Firm. Angela is a Board Certified Specialist in Family Law, certified by the North Carolina State Bar Board of Legal Specialization, and an experienced family law trial attorney who represents clients across North Carolina. She personally reviewed this page for legal accuracy.